
2027 ACA Marketplace MAGI & Premium Tax Credit Guide
Michigan / 48 Contiguous States & District of Columbia
Your Path to Better Coverage
KEY 2027 CHANGE
For 2027, Premium Tax Credit eligibility generally ends above 400% of the federal poverty line. Clients near that threshold should be handled carefully because changes in household income can materially affect final tax-credit eligibility and reconciliation.
1. 2027 Federal Poverty Guideline Reference
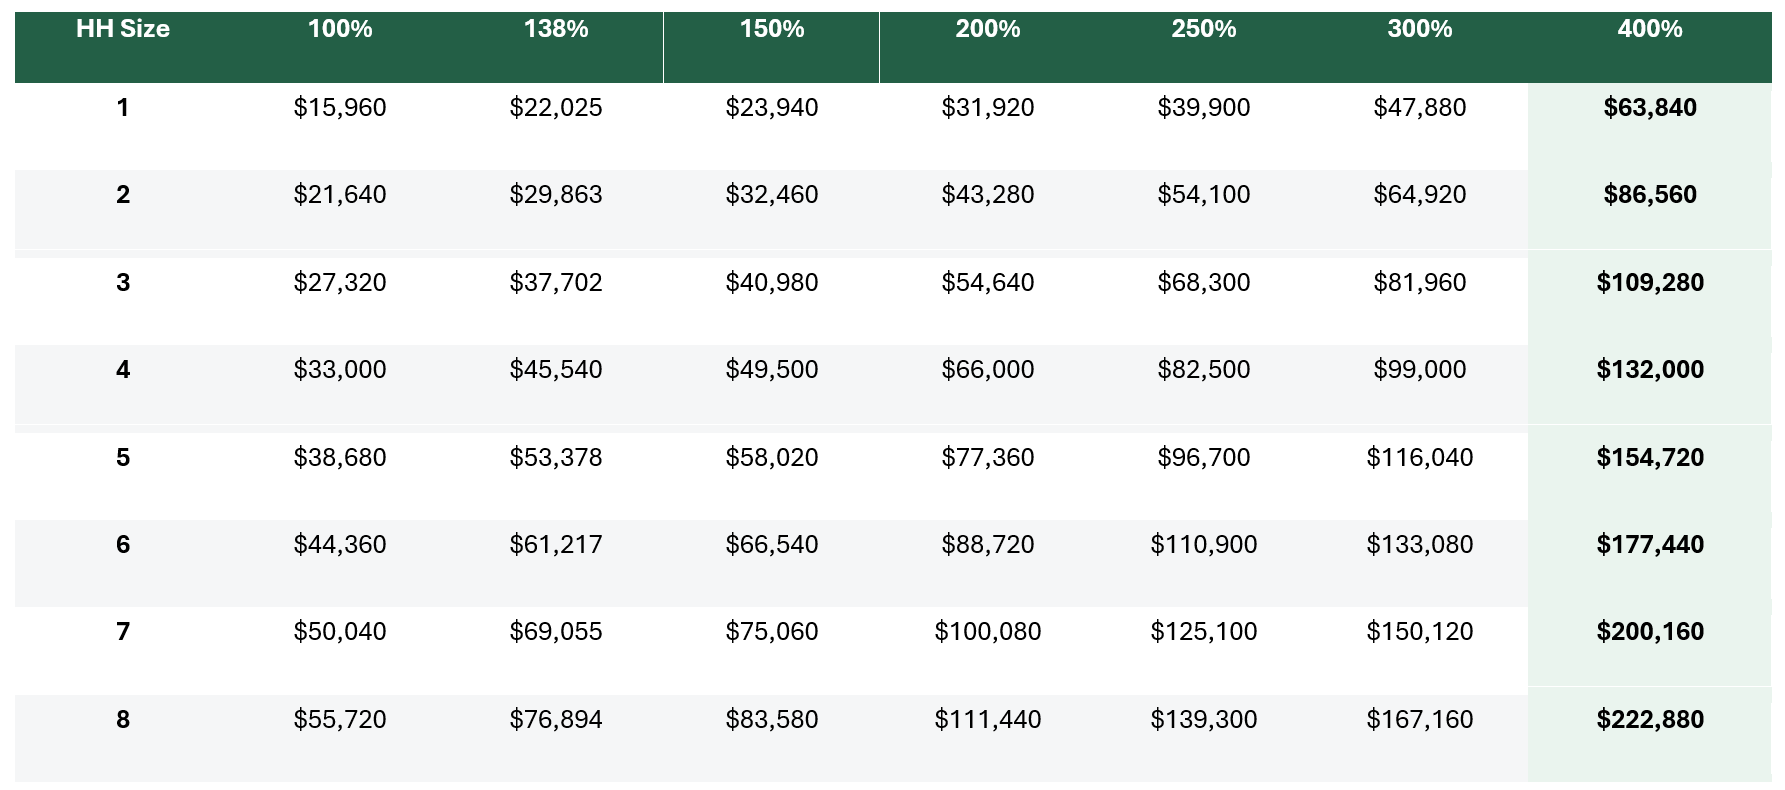
For Marketplace coverage in 2027, this guide uses the 2026 HHS poverty guidelines for the 48 contiguous states and D.C. The figures below are annual household-income reference amounts.
2. The 400% FPL Threshold
Agent focus: The temporary expansion that permitted PTC eligibility above 400% FPL applied through 2025. Current IRS guidance again generally limits PTC eligibility to household income from 100% through 400% FPL, subject to other eligibility requirements.
Example - two-person tax household: 400% FPL is $86,560. A household close to this level should be warned that year-end MAGI, not merely the initial estimate, determines the final allowable credit.
3. Marketplace MAGI - What Agents Should Review
· Start with federal Adjusted Gross Income (AGI).
· Add back nontaxable Social Security benefits.
· Add back tax-exempt interest.
· Add back excluded foreign earned income.
· Household income generally includes the MAGI of the taxpayer, spouse (when filing jointly), and tax dependents who are required to file a federal income tax return.
Common income items to watch: wages, self-employment income, taxable pension income, taxable IRA/401(k) distributions, capital gains, interest, dividends, rental income, unemployment compensation, and other taxable income. SSI is not included in Marketplace MAGI.
4. 2027 Applicable Percentage Table
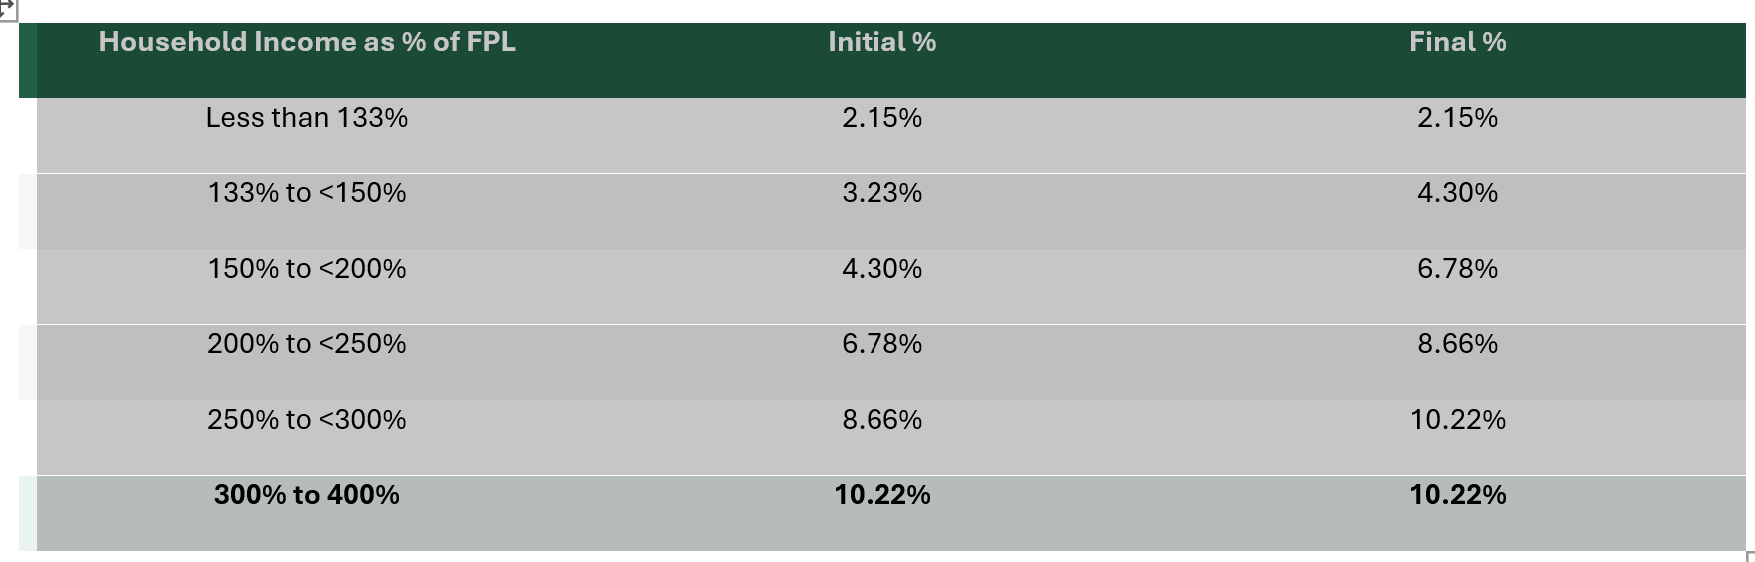
The IRS uses the following applicable percentages in the premium-tax-credit calculation for taxable year 2027. These percentages relate to the benchmark-plan contribution calculation; they are not a guarantee of what a client will pay for a particular plan.
5. Agent Workflow for Clients Near the Limit
1. Confirm the tax household size, not simply the number of people enrolled in the Marketplace plan.
2. Estimate full-year household MAGI using all expected income sources.
3. Ask specifically about Social Security, retirement distributions, Roth conversions, bonuses, capital gains, and self-employment income.
4. If projected income is close to 400% FPL, explain the reconciliation risk and encourage the client to consult a qualified tax professional.
5. Update Marketplace income estimates when circumstances materially change during the year.
6. Document that tax-credit eligibility is determined under federal tax rules and that the agency is not providing tax advice.